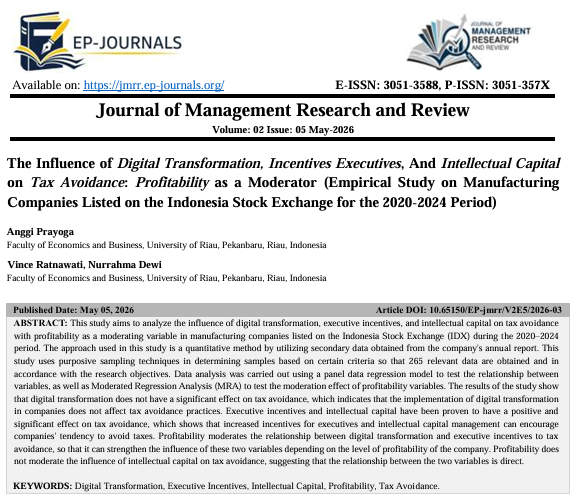
The Influence of Digital Transformation, Incentives Executives, And Intellectual Capital on Tax Avoidance: Profitability as a Moderator (Empirical Study on Manufacturing Companies Listed on the Indonesia Stock Exchange for the 2020-2024 Period)
DOI:
https://doi.org/10.65150/EP-jmrr/V2E5/2026-03Keywords:
Digital Transformation, Executive Incentives, Intellectual Capital, Profitability, Tax Avoidance.Abstract
This study aims to analyze the influence of digital transformation, executive incentives, and intellectual capital on tax avoidance with profitability as a moderating variable in manufacturing companies listed on the Indonesia Stock Exchange (IDX) during the 2020–2024 period. The approach used in this study is a quantitative method by utilizing secondary data obtained from the company's annual report. This study uses purposive sampling techniques in determining samples based on certain criteria so that 265 relevant data are obtained and in accordance with the research objectives. Data analysis was carried out using a panel data regression model to test the relationship between variables, as well as Moderated Regression Analysis (MRA) to test the moderation effect of profitability variables. The results of the study show that digital transformation does not have a significant effect on tax avoidance, which indicates that the implementation of digital transformation in companies does not affect tax avoidance practices. Executive incentives and intellectual capital have been proven to have a positive and significant effect on tax avoidance, which shows that increased incentives for executives and intellectual capital management can encourage companies' tendency to avoid taxes. Profitability moderates the relationship between digital transformation and executive incentives to tax avoidance, so that it can strengthen the influence of these two variables depending on the level of profitability of the company. Profitability does not moderate the influence of intellectual capital on tax avoidance, suggesting that the relationship between the two variables is direct.
References
1) Barney, J. (1991). Strong resources and continuous competitive advantage. Journal of Management, 17, 99–120.
2) Chen, W., & Meng, F. (2024). Is a company's digital transformation a tax haven? International Journal of Managerial Finance, 20(2), 304–333. https://doi.org/10.1108/IJMF-11-2022-0505
3) Dewi, N. L. P., & Noviari, N. (2017). The Influence of Company Size, Leverage, Profitability and Corporate Social Responsibility on Tax Avoidance. E-Journal of Accounting of Udayana University, 21(1), 830–855.
4) Eisenhardt, KM (1989). Accessibility support: If you encounter accessibility issues with this file, report here Agency Theory: Assessment and Review. In Source: Academy of Management Review (Vol. 14, Number 1). https://www.jstor.org/stable/258191
5) Hanelt, A., Bohnsack, R., Marz, D., & Antunes Marante, C. (2021). A Systematic Review of the Literature on Digital Transformation: Insights and Implications for Organizational Strategy and Change. Journal of Management Studies, 58(5), 1159–1197.
https://doi.org/10.1111/joms.12639
6) Hidayatulloh, T., Tanzil, N. D., & Priyono, A. P. (2024). Digital Transformation, Media Attention, and Tax Avoidance: A Study of Indonesian Multinationals. Journal of Accounting, Finance, and Management, 6(1), 231–243.
https://doi.org/10.35912/jakman.v6i1.3735
7) Jensen, M.C., & Meckling, W.H. (1976). Company theory: Managerial behavior, agency costs, and ownership structures. Journal of Financial Economics, 3(4), 305–360. https://doi.org/https://doi.org/10.1016/0304-405X(76)90026-X
8) Nabila, & Ramdani, E. (2022). The Effect of Executive Incentives and Company Size on Tax Avoidance Empirical Study on Manufacturing Companies in the Sub-Sector of Various Industries Listed on the Indonesia Stock Exchange (IDX) in 2017-2020. Asian Journal of Management Analytics, 1(1), 51–62. https://doi.org/10.55927/ajma.v1i1.1394
9) Rahmi, N., Azwirman, & Novriadi. (2024). The Influence of Good Corporate Governance (GCG), Corporate Social Responsibility (CSR), and Intellectual Capital on Tax Avoidance. Journal of Accounting, 14(1), 25–41.
10) Ratnawati, V., Freddy, D., & Hardi, H. (2018). Ownership Structure, Tax Avoidance, and Company Performance. Business Research Archive, 6(1). https://doi.org/10.14738/abr.61.4011 11) Scholes, MS . . . (2014). Tax and business strategy. Prentice Room.
11) Silviana, V., & Sumantri, I. I. (2023). The Influence of Good Corporate Governance, Executive Incentives, Deferred Tax Expense on Tax Avoidance (Empirical Study on Mining Sector Companies Listed on the Indonesia Stock Exchange for the 2016-2020 Period). In Journal Of Applied Managerial Accounting (Vol. 7, Number 1).
12) Stawati, V. (2020). The influence of profitability, leverage and company size on tax avoidance. Journal of Accounting and Business. https://doi.org/10.31289/jab.v6i2.3472
13) Tiantian, G., Hailin, C., Zhou, X., Ai, S., & Siyao, W. (2023). Does a company's digital transformation affect the company's tax avoidance rate? Empirical evidence from tourism companies registered in China. Financial Research Letters, 57, 104271.
https://doi.org/https://doi.org/10.1016/j.frl.2023.104271
14) Verhoef, P.C., Broekhuizen, T., Bart, Y., Bhattacharya, A., Qi Dong, J., Fabian, N., & Haenlein, M. (2021). Digital transformation: Multidisciplinary reflection and research agenda. Journal of Business Research, 122, 889–901.
https://doi.org/10.1016/j.jbusres.2019.09.022
15) Widodo, Y. A., Kharisma Utami, C., & Nurfauziah, F. L. (2022). The Effect of Investment Opportunity Set (IOS) and Intellectual Capital on Tax Avoidance. www.idx.co.id.
16) Zhang, Q., & She, J. (2024). Digital transformation and corporate tax avoidance: Analysis based on various perspectives and mechanisms. PloS One, 19(9), e0310241. https://doi.org/10.1371/journal.pone.0310241
Downloads
Published
Issue
Section
License
Copyright (c) 2026 Anggi Prayoga , Vince Ratnawati, Nurrahma Dewi (Author)

This work is licensed under a Creative Commons Attribution 4.0 International License.